Why fintech infrastructure is consolidating — and what it means for you
Businesses used to stitch together five different tools for accounts, payments, and cards. That is changing fast. Here is why, and what to look for in a consolidated platform.
Marcus Ohene
International Payments Lead · September 2, 2025
Five years ago, a growing business might have used a separate bank for accounts, a separate provider for international payments, a separate card issuer, and a separate expense management tool — each with its own login, its own reconciliation process, and its own support line. That model is disappearing.
The reconciliation tax
Every additional tool in the stack adds a reconciliation cost that scales with transaction volume, not headcount. A finance team processing ten times the payment volume with the same headcount is spending an outsized share of their time just matching records across systems — time that a consolidated platform gives back.
Data as the real product
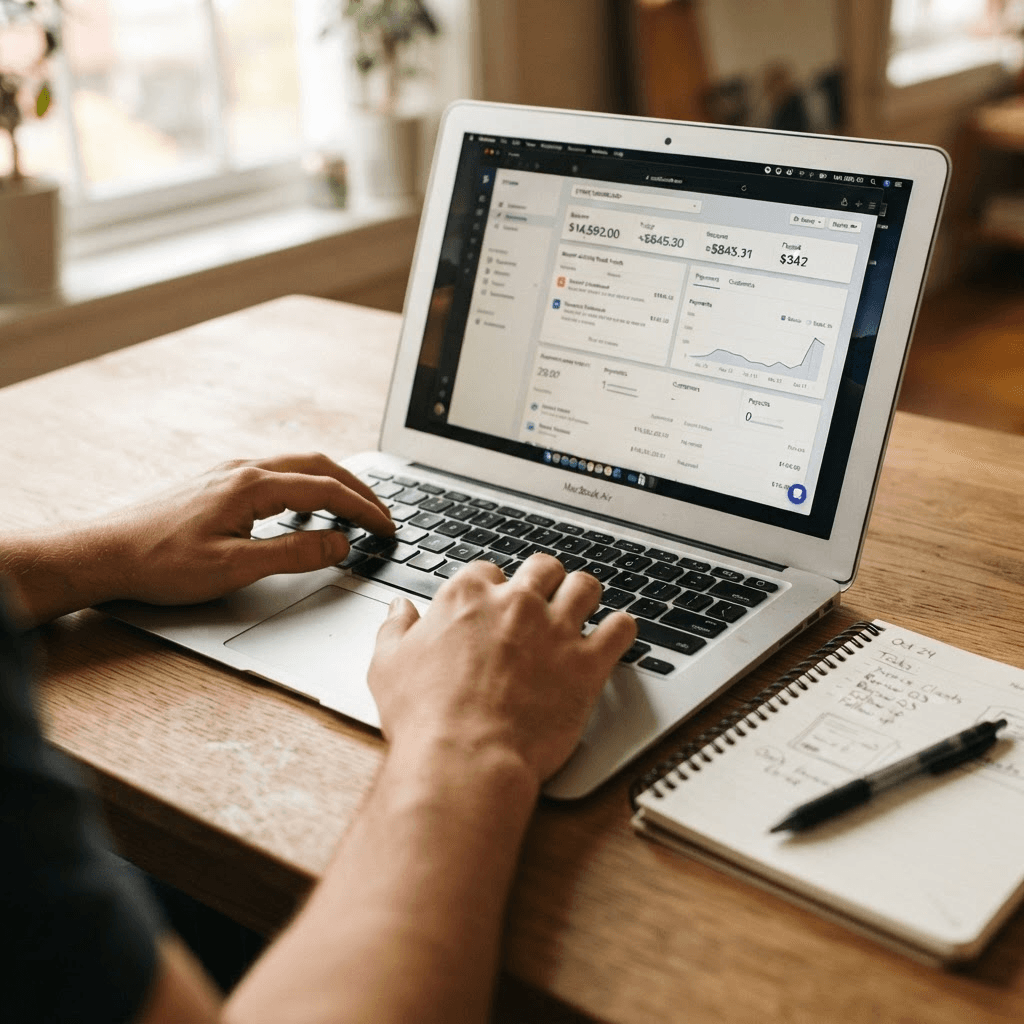
When accounts, payments, and cards live on separate platforms, you never get a real-time, complete view of cash position — you get five partial views that need manual assembly. Consolidation is really about that unified view being available the moment a transaction happens, not at month-end.
What to actually evaluate
Not every "all-in-one" platform is equally consolidated under the hood — some are five acquired products wearing one login page. Ask specifically whether balances, payments, and cards share one ledger and one permission system, or whether they are separate systems with a shared UI layered on top. The answer changes how much of the reconciliation tax you actually avoid.